One clear thing to do.
Not a page of everything. One question you can answer, and a sense of where it sits.
The biggest form most people will ever fill in, at the most nervous moment of their financial life.
One thing to know before you start: in the US, a mortgage application is a federal form. What it contains is set by law, not by the bank and certainly not by a designer. This is not a story about deleting questions.
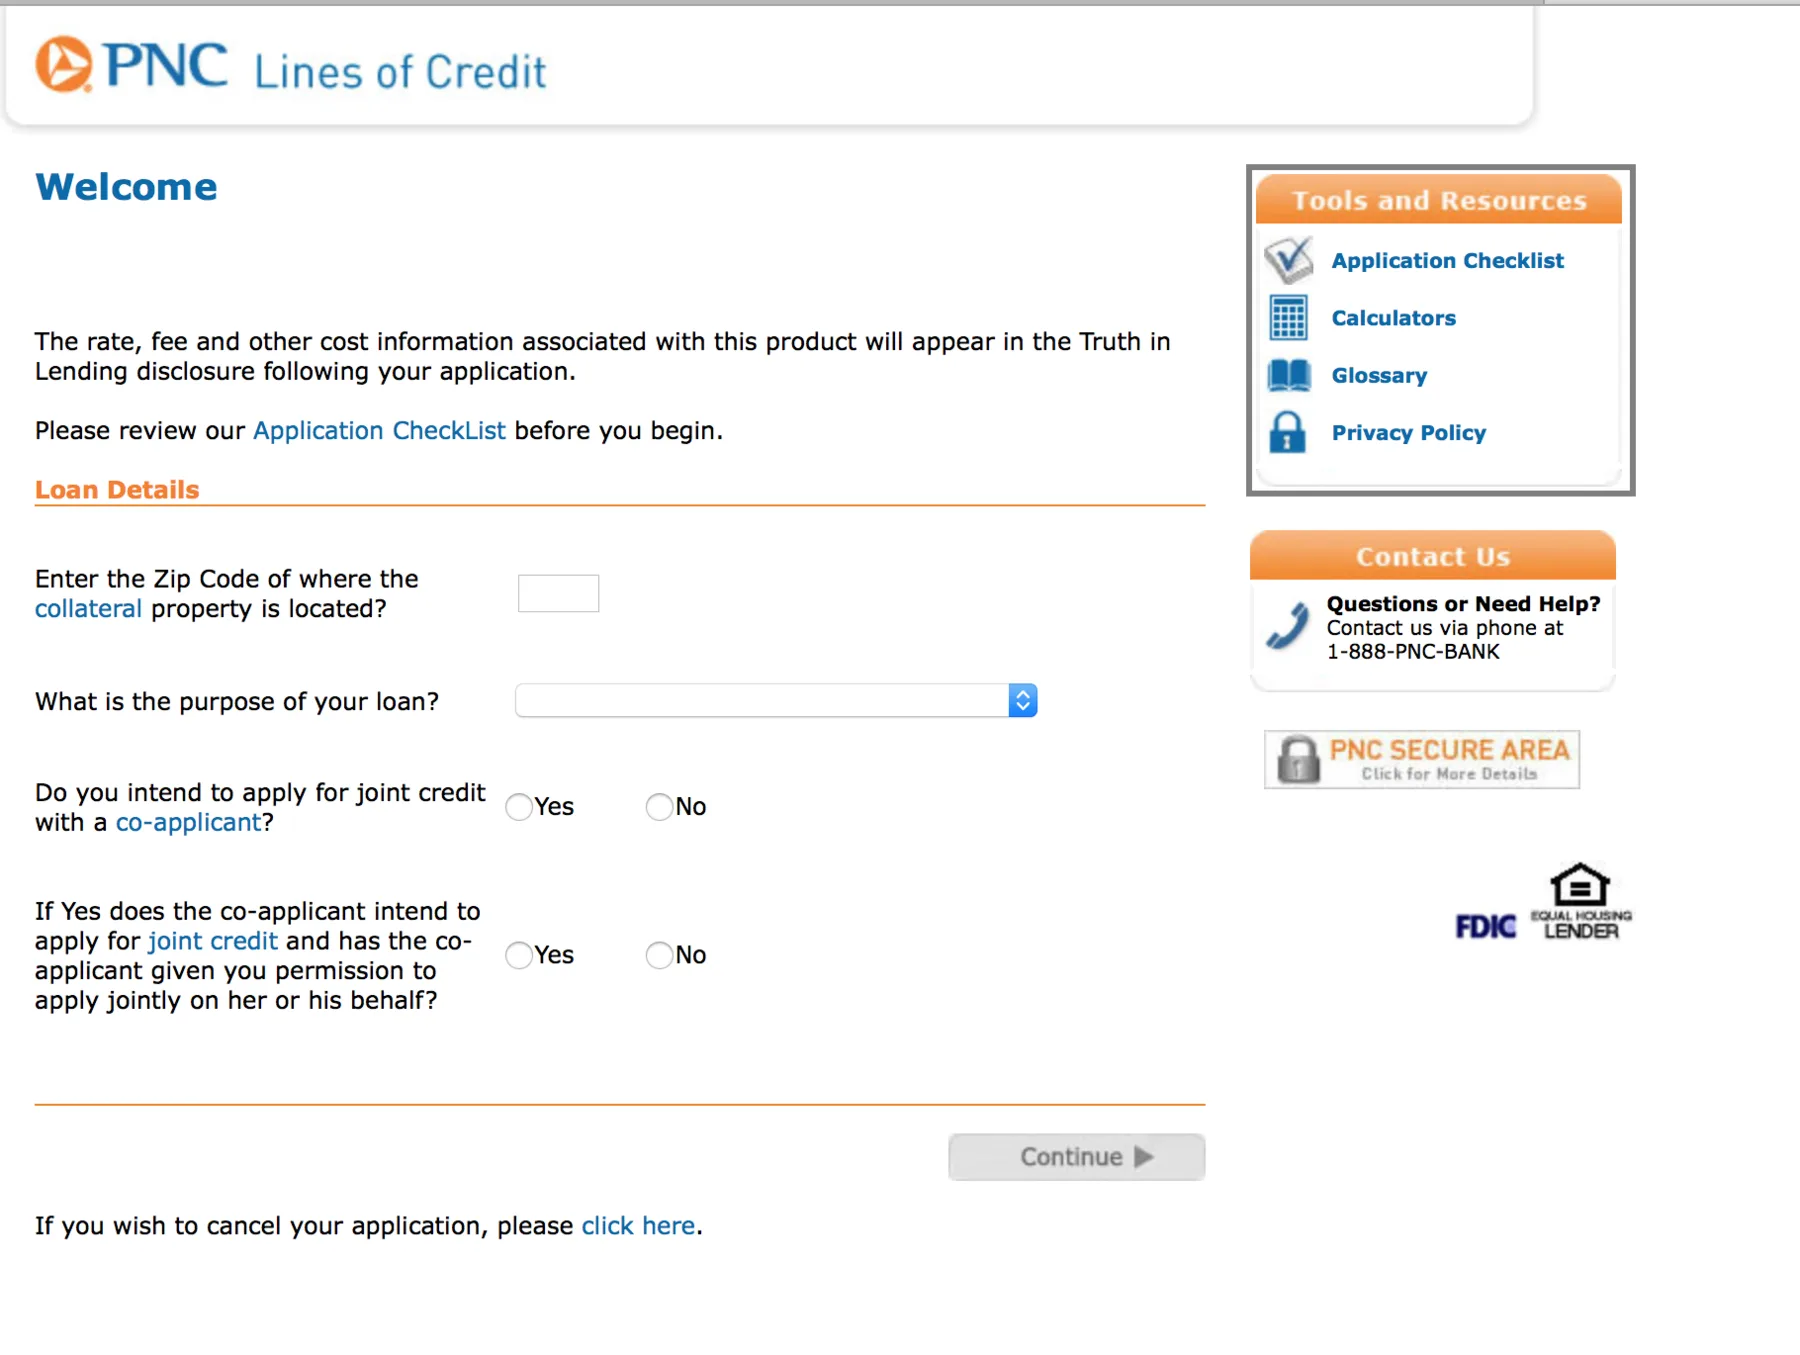
The old application put every question a bank might ever need in front of everyone.
Rental income. Business ownership. Your other properties. Most of it belonged to somebody else’s situation.
For any one borrower, only a handful of these were ever actually theirs.
Occupancy: will you live there, or rent it out. Declarations: a fixed block of legal yes/no questions everyone must answer. Income verification: proof that what you earn is real. Property schedule: the other homes you own. Meaningless to a first-time buyer, and the old form asked everybody.
Should I be filling this out?
This sentence came up again and again in testing, and it is worse than “too long.” People read an irrelevant question as evidence they had got something wrong. A form that asks you the wrong question makes you doubt yourself.
A mortgage application is a federal form, set by law and by the organisations that buy mortgages from banks. It was never a design decision.
So the job was never removing questions. It was working out which ones belonged to you, and when.
The requirements stayed exactly where they were. The burden of meeting them is what moved.
Not a page of everything. One question you can answer, and a sense of where it sits.
Your answers decide what comes next. Questions that were never yours never appear.
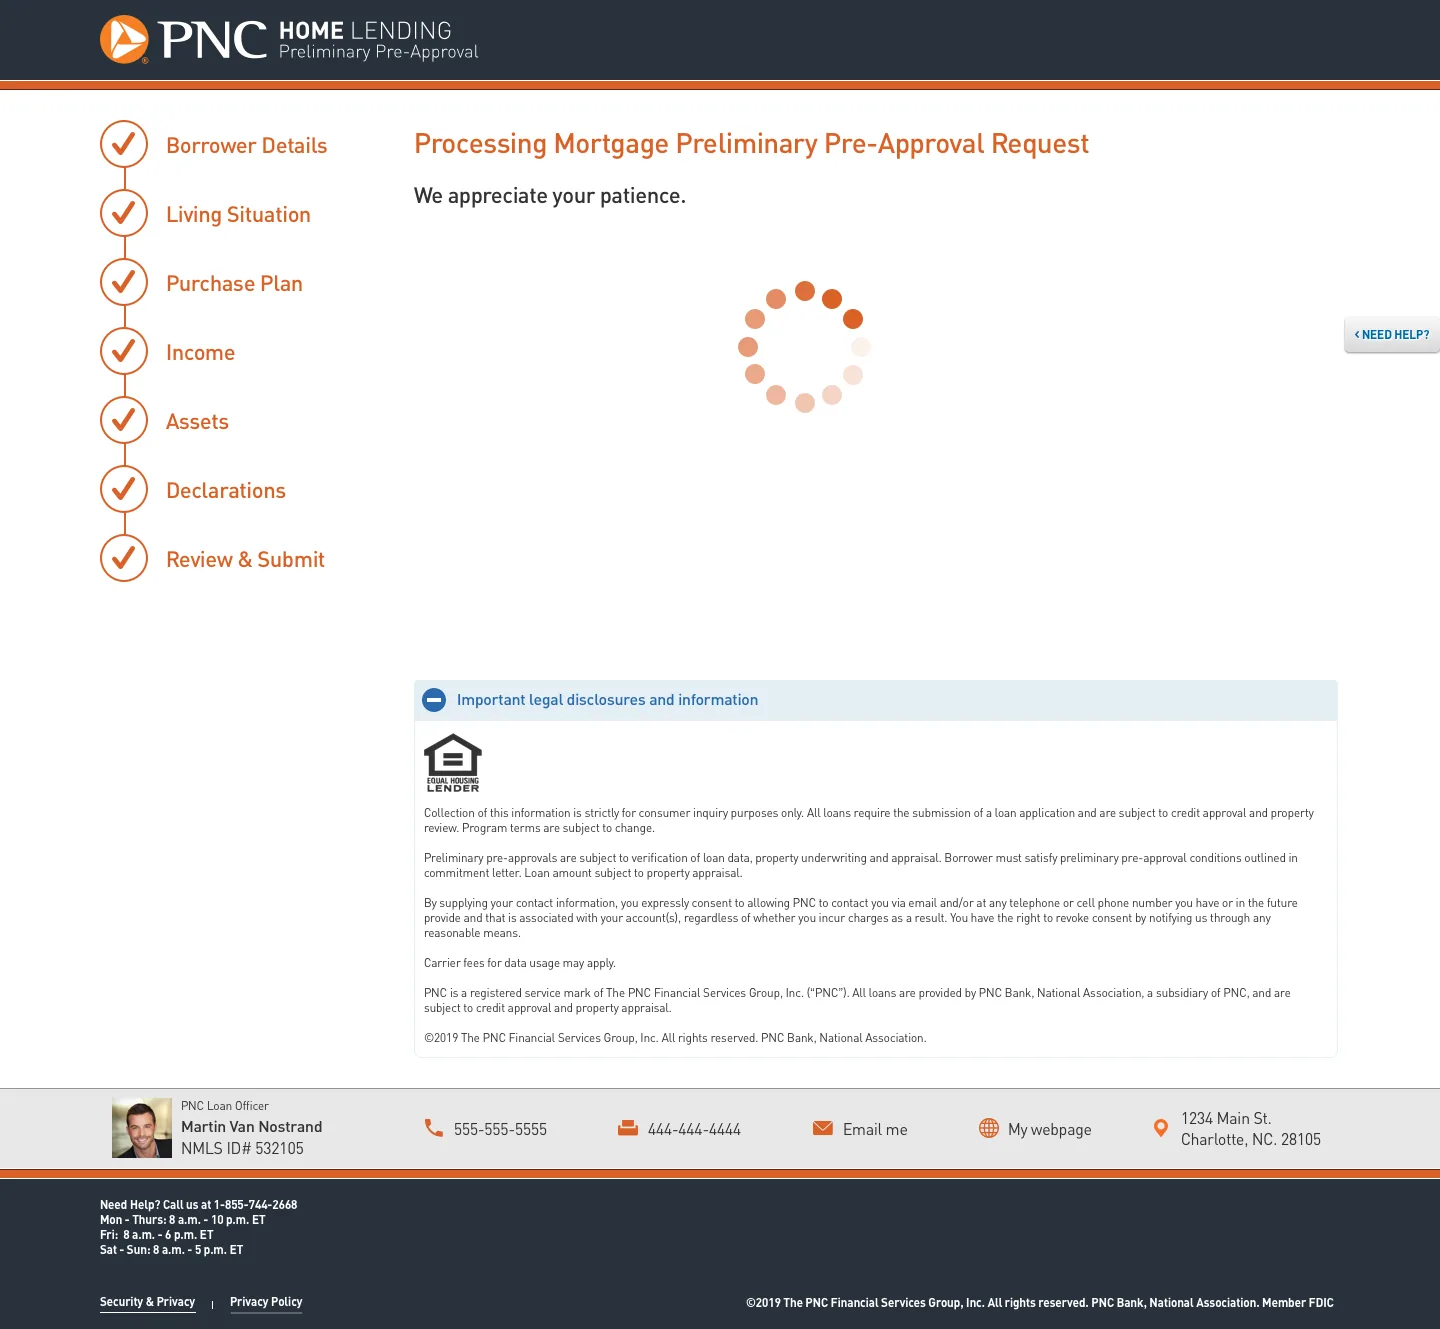
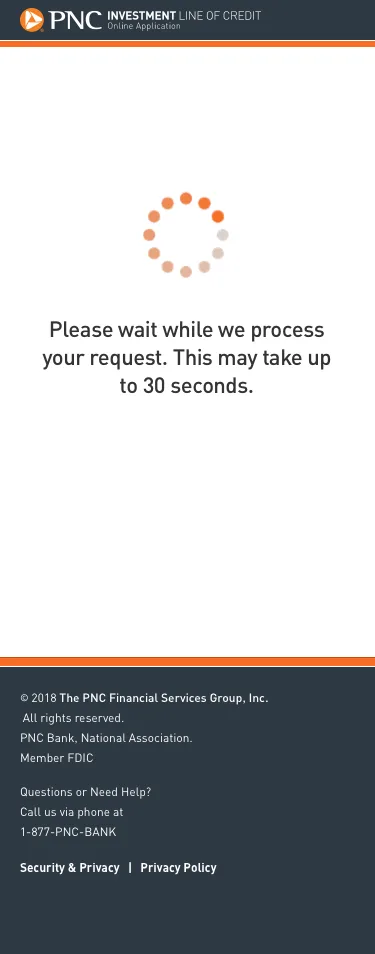
The most anxious moment in the process. It explains what is happening instead of showing a spinner.
You read back the path you actually took, not another wall of fields.
The result, the detail behind it, one next step. Same on a laptop as on the phone you started on.
A calmer surface, because the logic underneath is doing more work.
Not a concept. Real people apply for real mortgages through PNC Home Lending, and real loan officers review them on the other side. Live for years.
That’s the story. There’s more underneath it.
What I was hired to do, how I led it, and what is live in production today.
In the US a mortgage application is a federal form. What it must contain is set by law and by the organisations that buy mortgages from banks afterwards, like Fannie Mae. A designer cannot delete a question.
The customer applying, and the loan officer who reviews and approves it. Everything vague on the customer’s side becomes a phone call and a correction on the officer’s. Fixing one by burdening the other would not have counted.
Not whether to ask, but which questions belong to which person, and when. The old form asked everyone everything; for any one borrower only a handful of those questions were ever actually theirs.
Main home, second home or rental. It changes your rate and the rules.
A fixed block of yes/no questions everybody has to answer. Not removable.
Payslips, tax returns, employer confirmation. Genuinely mandatory.
Meaningless to a first-time buyer. The old form asked everybody.
None of the information was optional. The burden created by its presentation was.
Everyone assumed the whole form was required by law. Mapping the journey made the real dependencies visible: what the customer knew at each point, what paperwork they actually had to hand, and what the bank was obliged to check. That separated the genuine legal requirements from habits inherited from the old system, and the entire design opportunity lived in that gap.
Whether you are buying or remortgaging, what kind of property, who is applying — those answers decide what appears next. The application still captures everything the law requires. It just stops showing you the parts that were never yours, so a question that does not apply never becomes a reason to doubt yourself.
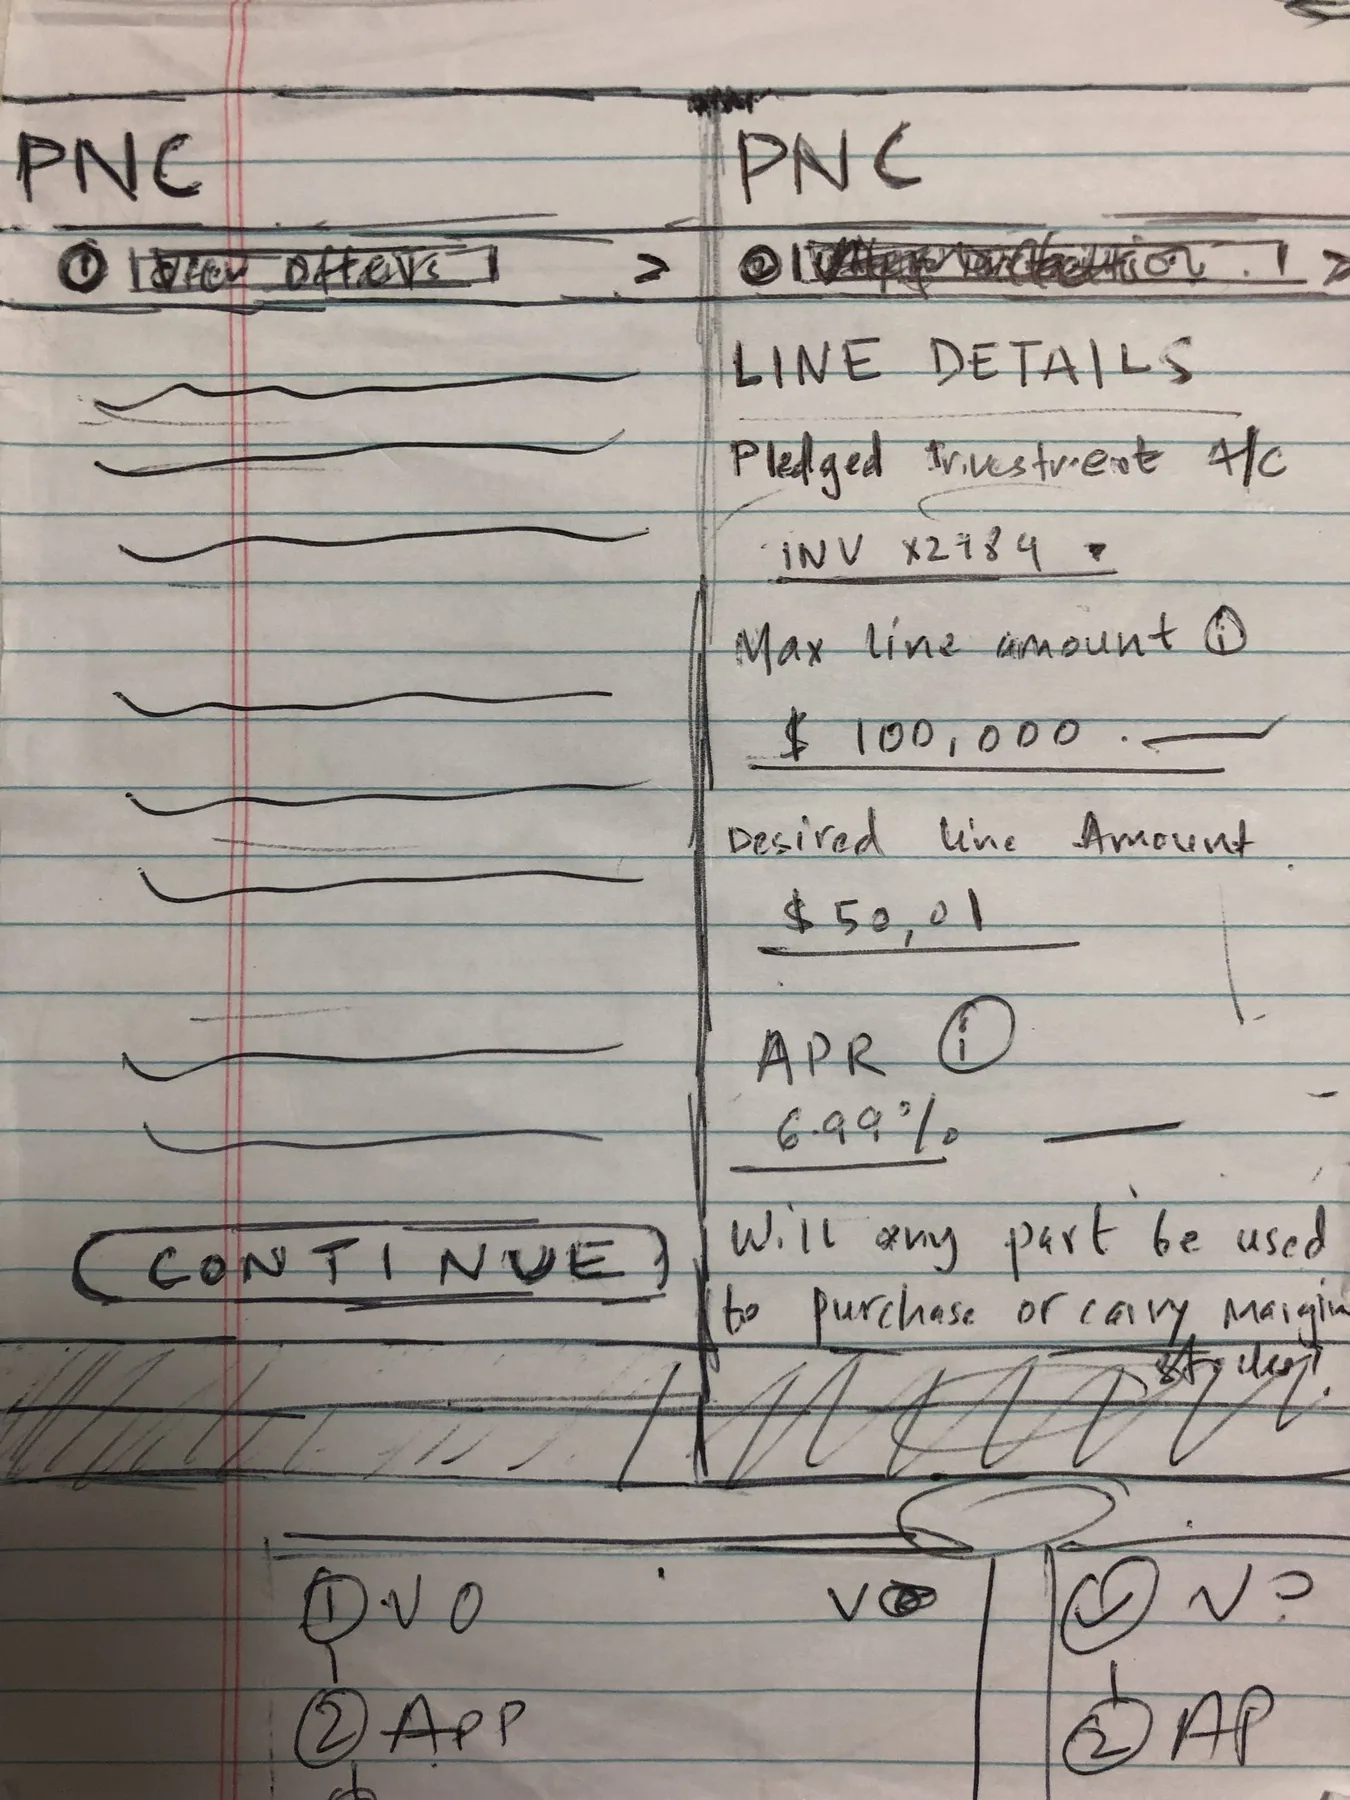
Sketches on paper are cheap to throw away, and they answer the only question that matters first: does the order make sense. Rough grey layouts test what is prominent and whether the wording lands, without anyone arguing about colour. The shared component kit proved the patterns repeated across teams and screen sizes. Anything that looked finished came last, once the behaviour had earned it.
Every two weeks ended with something working, concrete enough for legal, compliance, engineering and marketing to react to. Constraints arrived while they could still shape the design, instead of as a veto at the end — and real customers saw it every six to eight weeks throughout.
Eight real pieces of the work, labelled by the kind of thinking each one needed. Click any of them to view full size. Arrow keys move through the set.
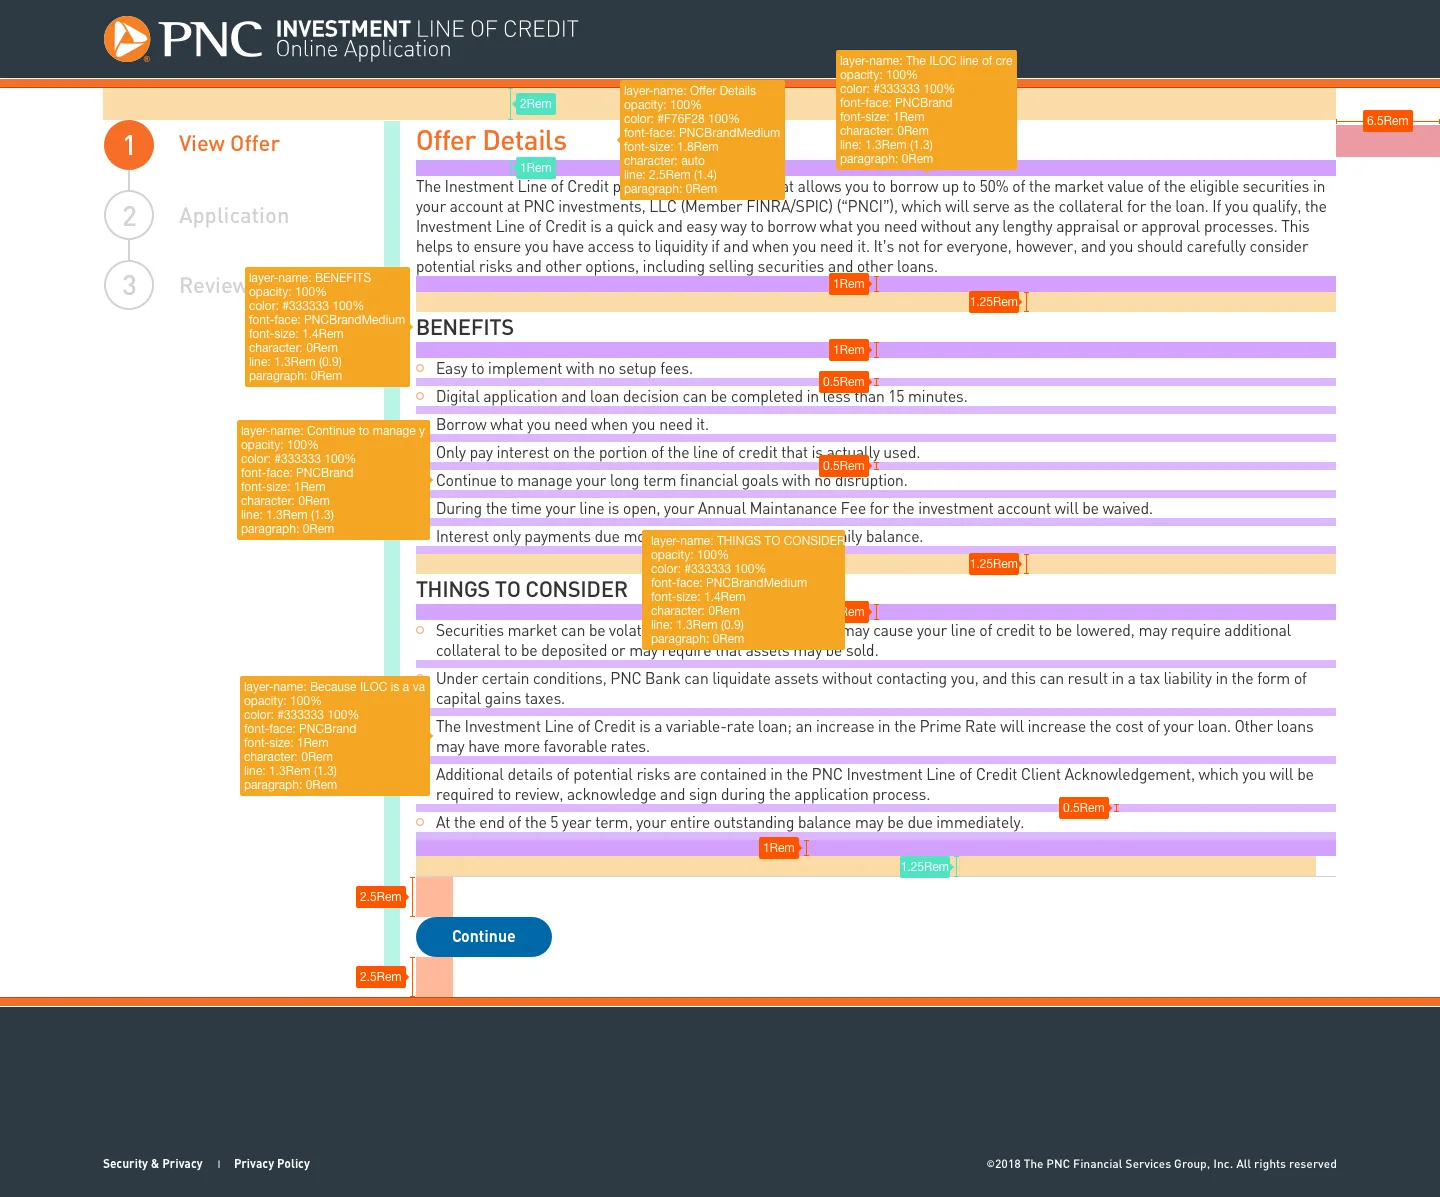
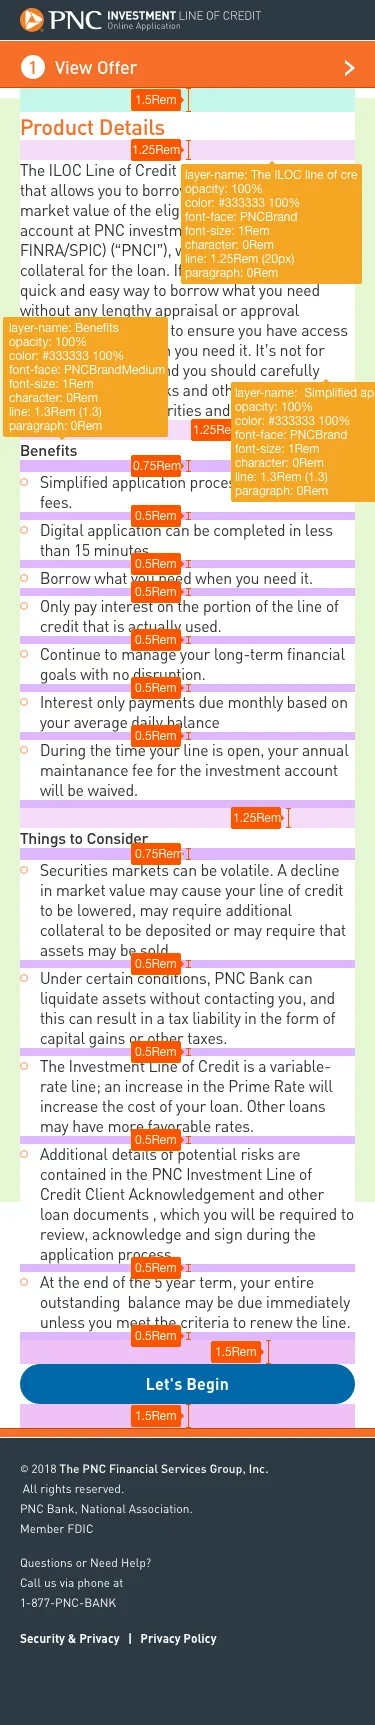
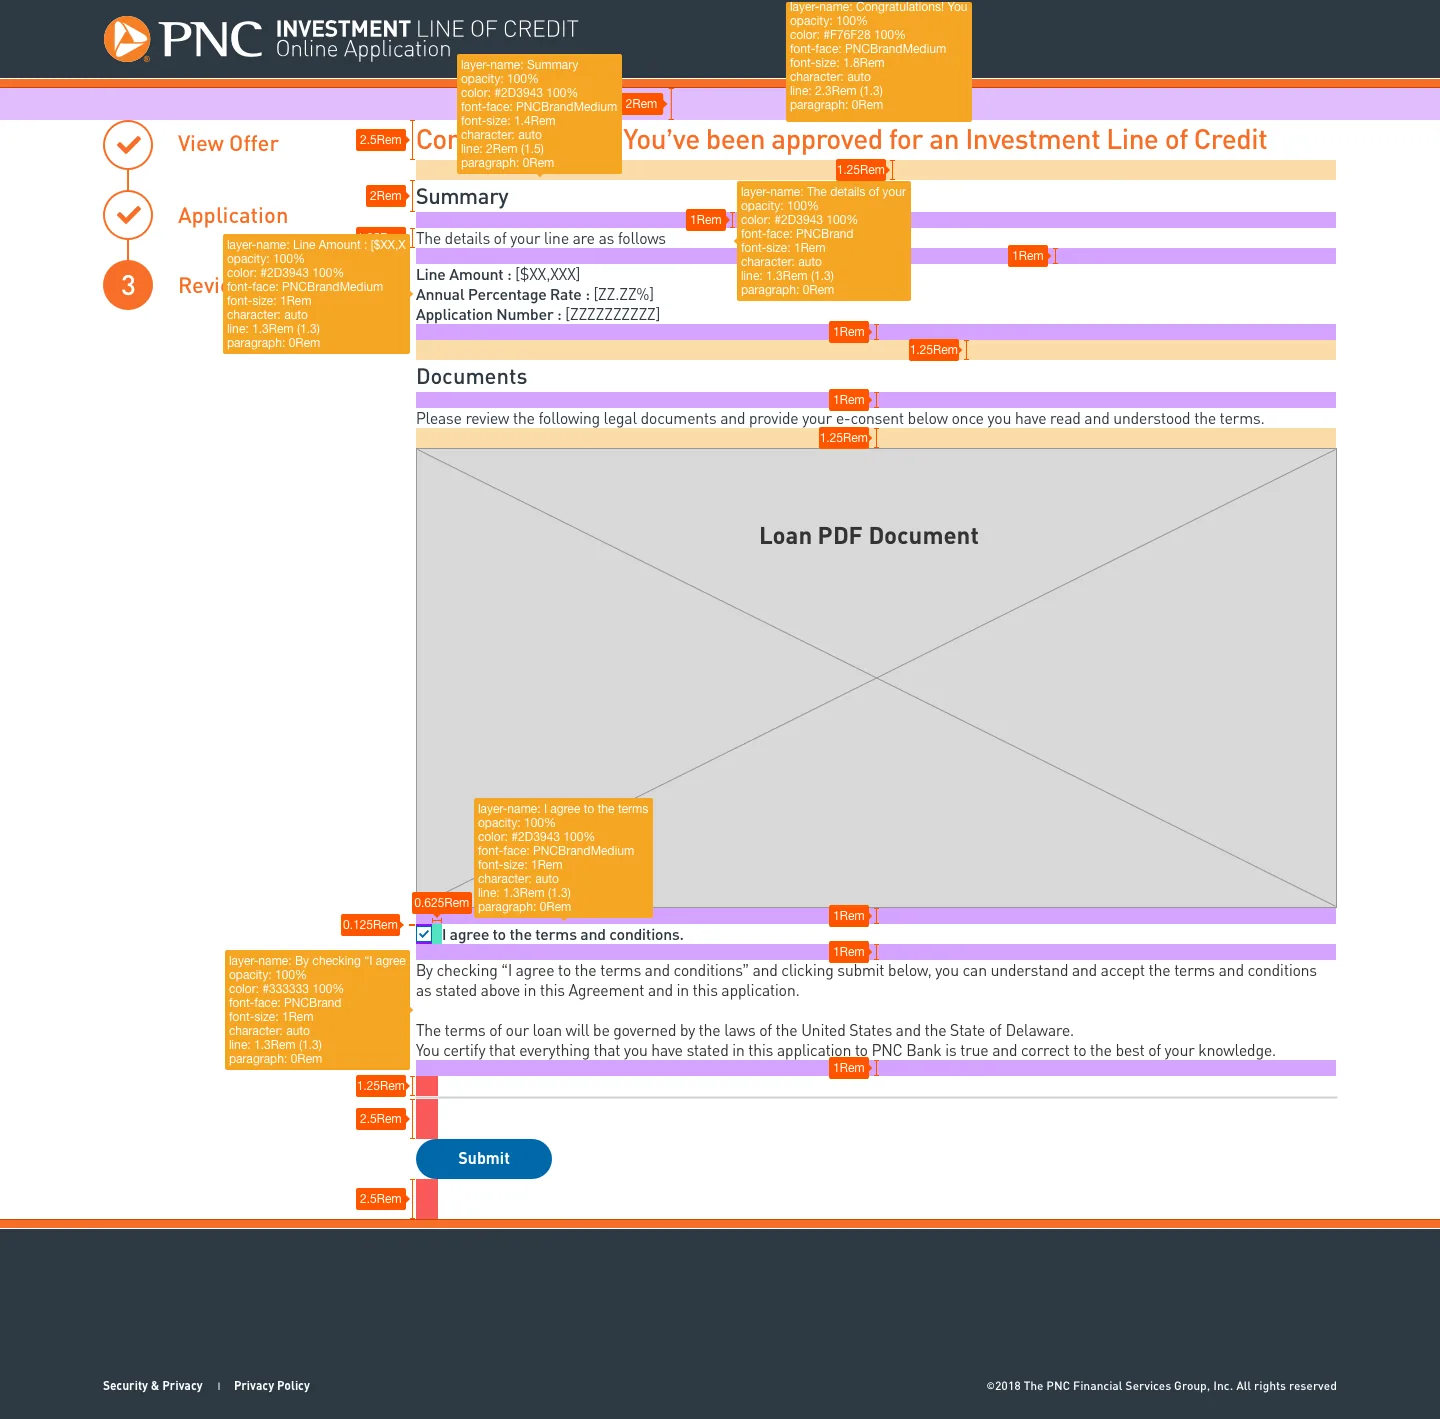
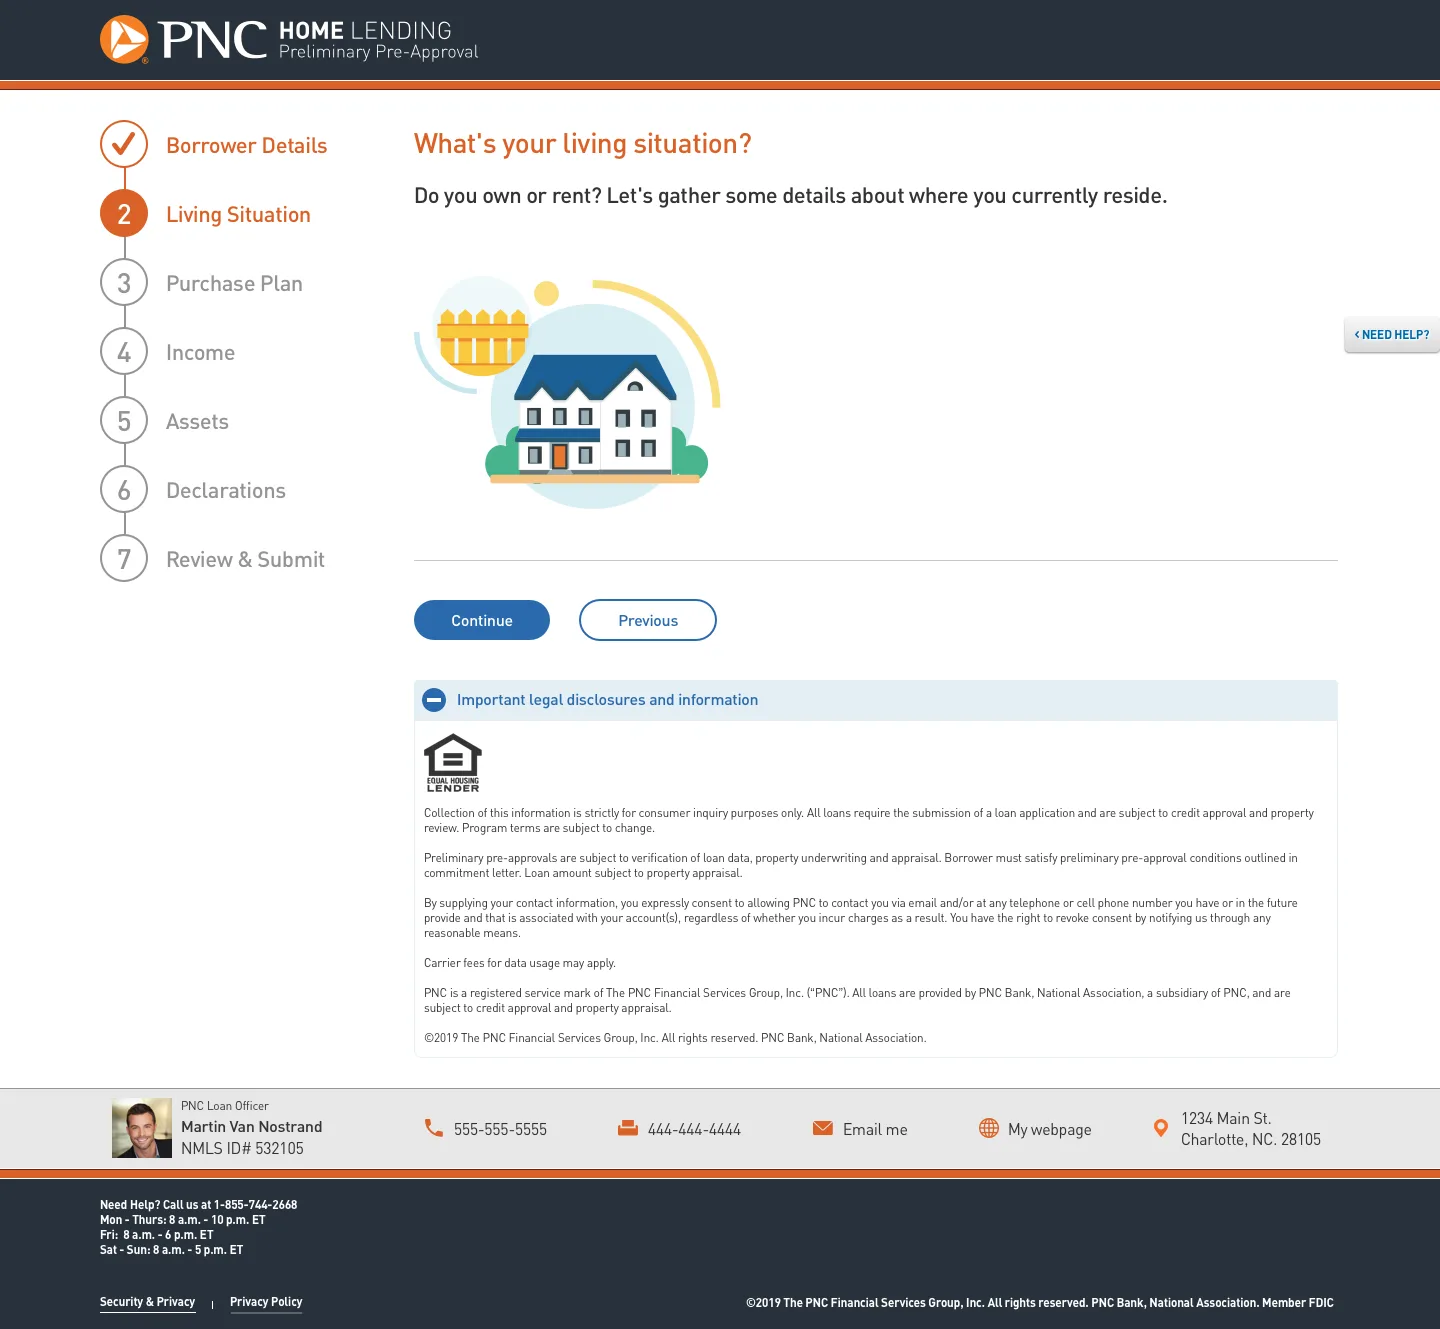
The same parts, the same error checks and your saved progress keep laptop and phone as one experience, rather than two products that happen to look alike.
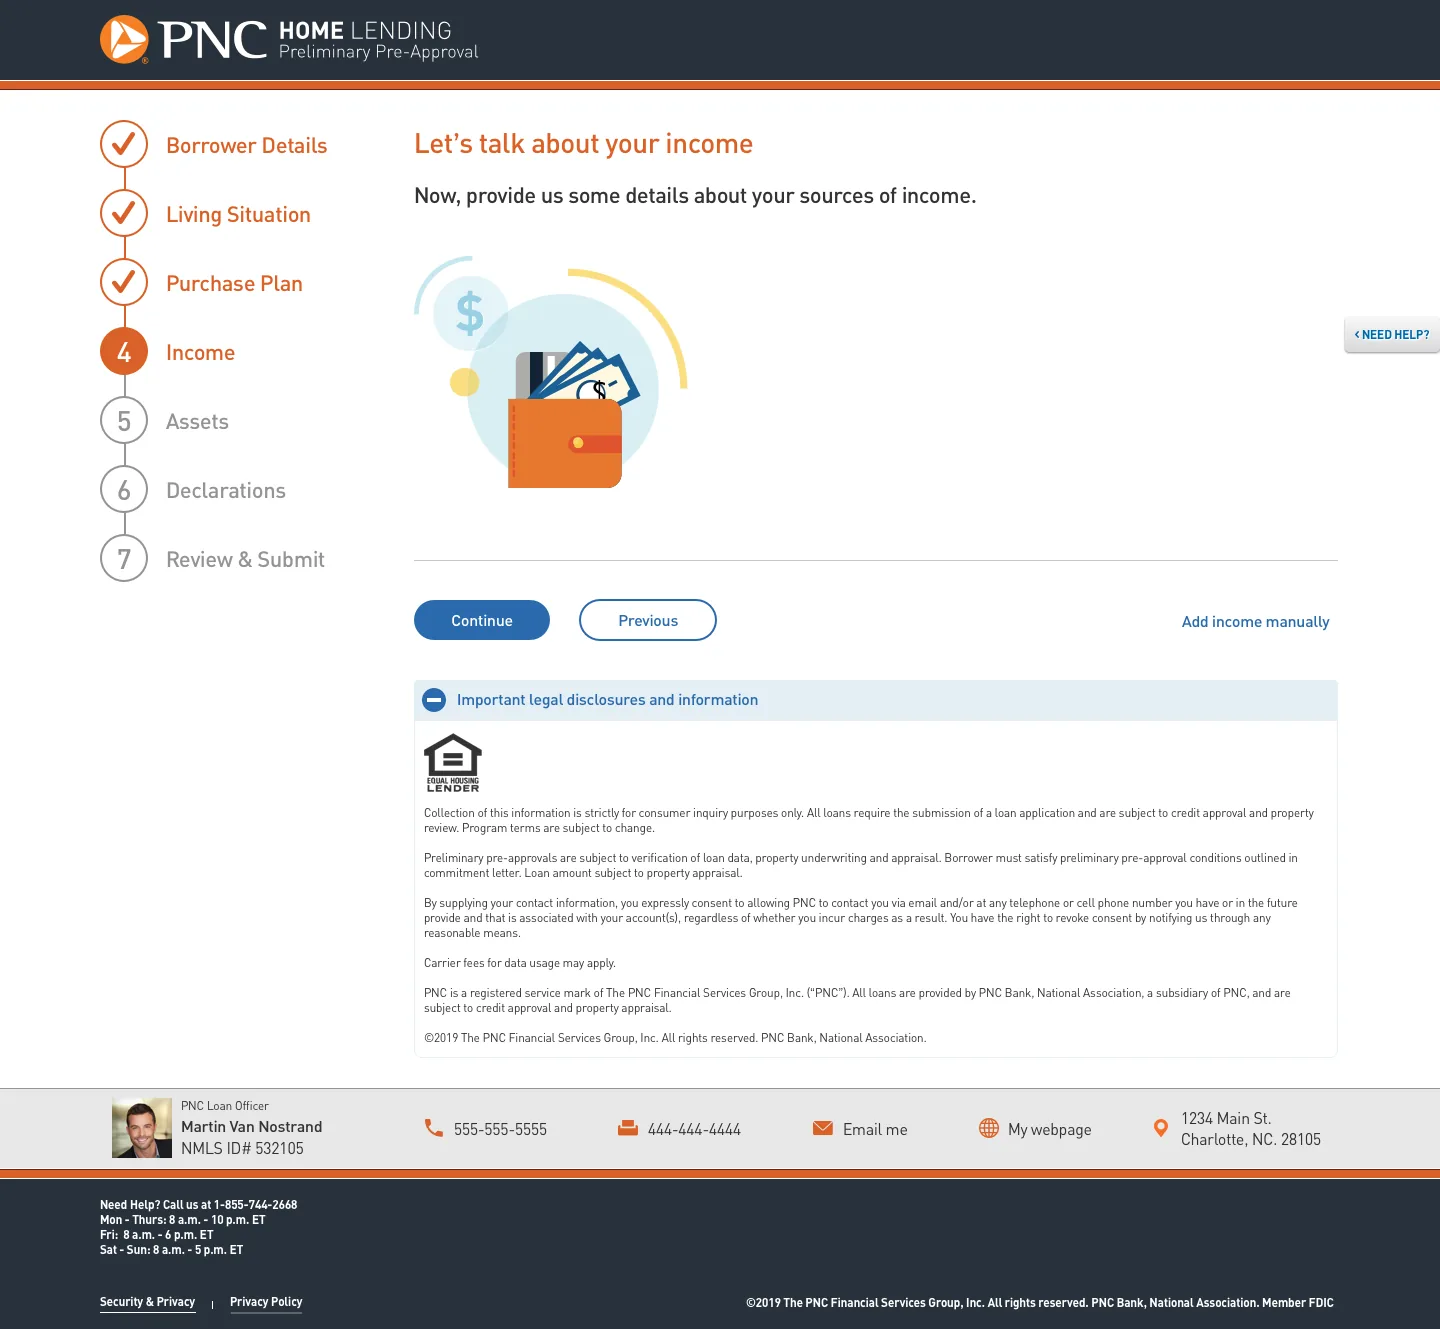
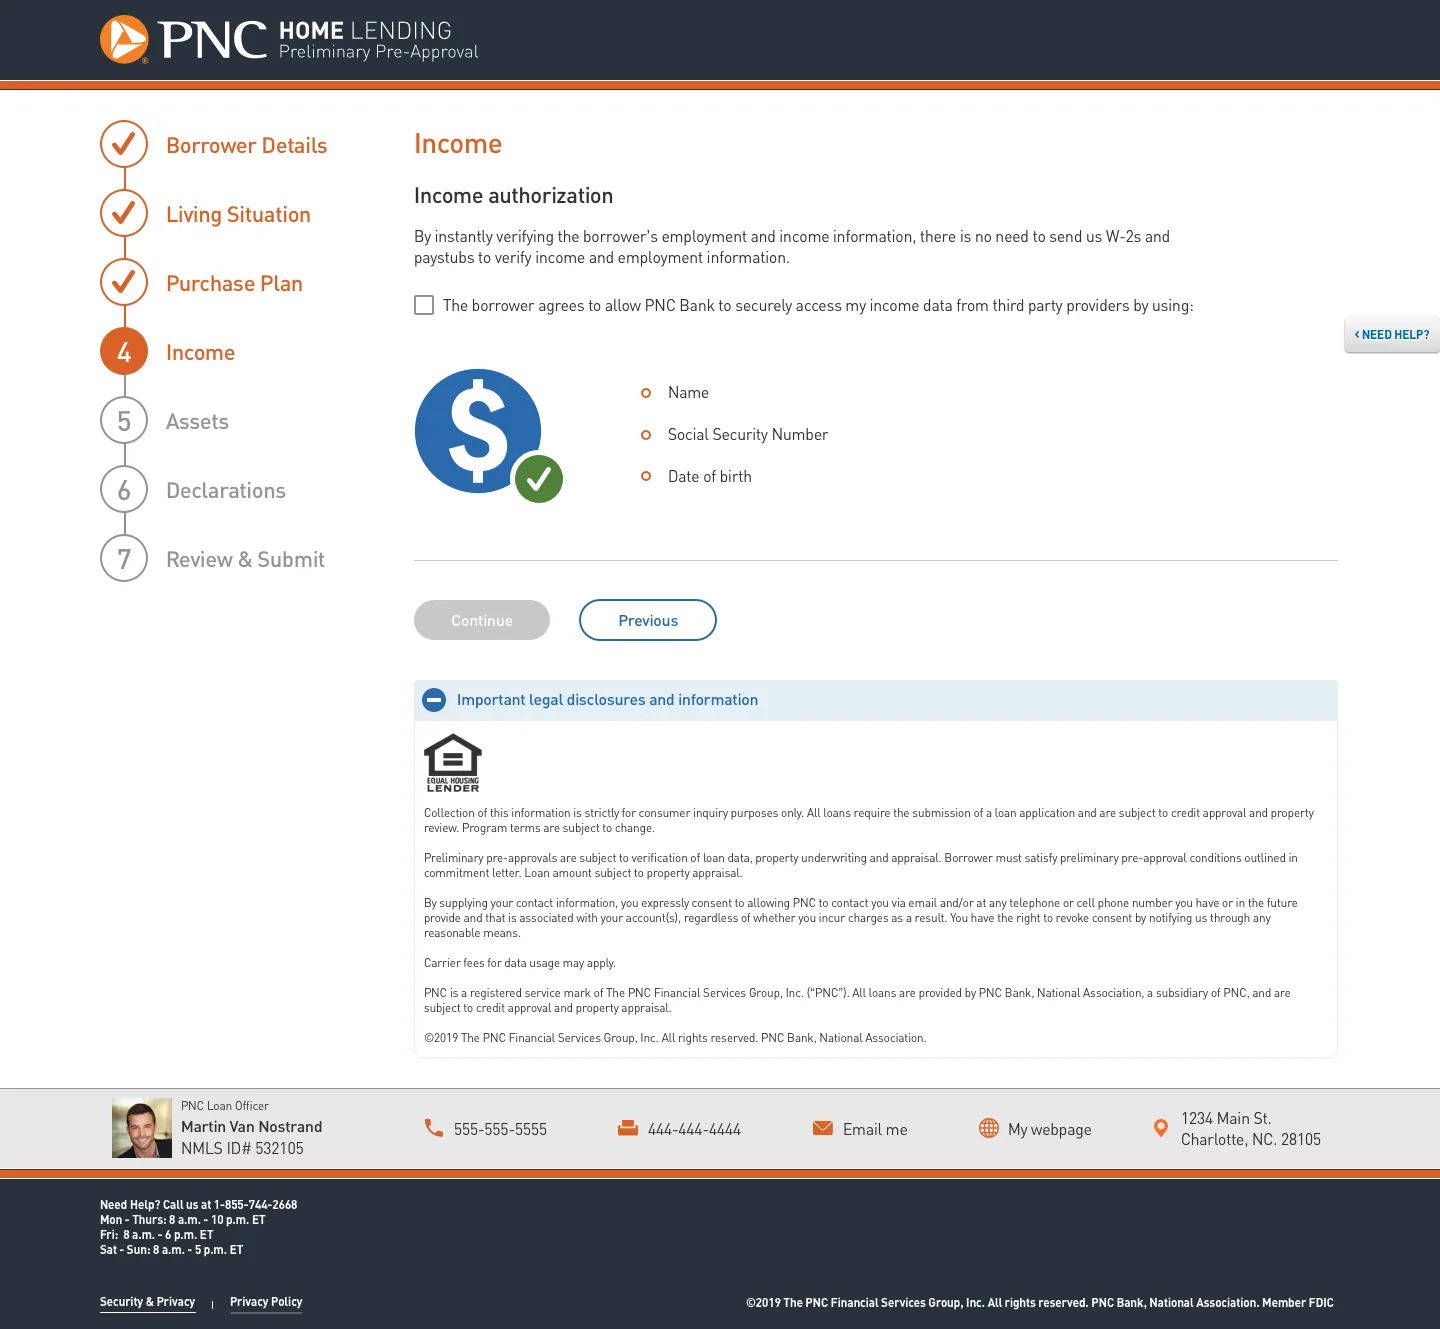
Income and application details arrive in order on either screen, with a progress indicator that reflects the path you are actually on — not a generic one.
SHARED SEQUENCE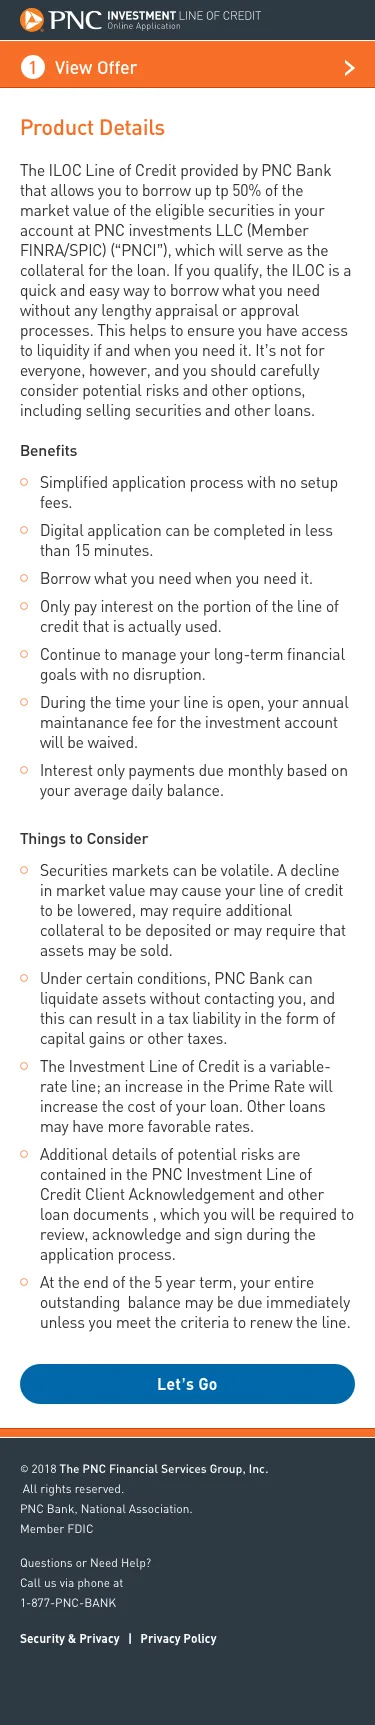
The offer step is rebuilt for the phone around a single choice, using the same wording and the same checks as the laptop version.
REBUILT FOR THE PHONE, NOT SHRUNK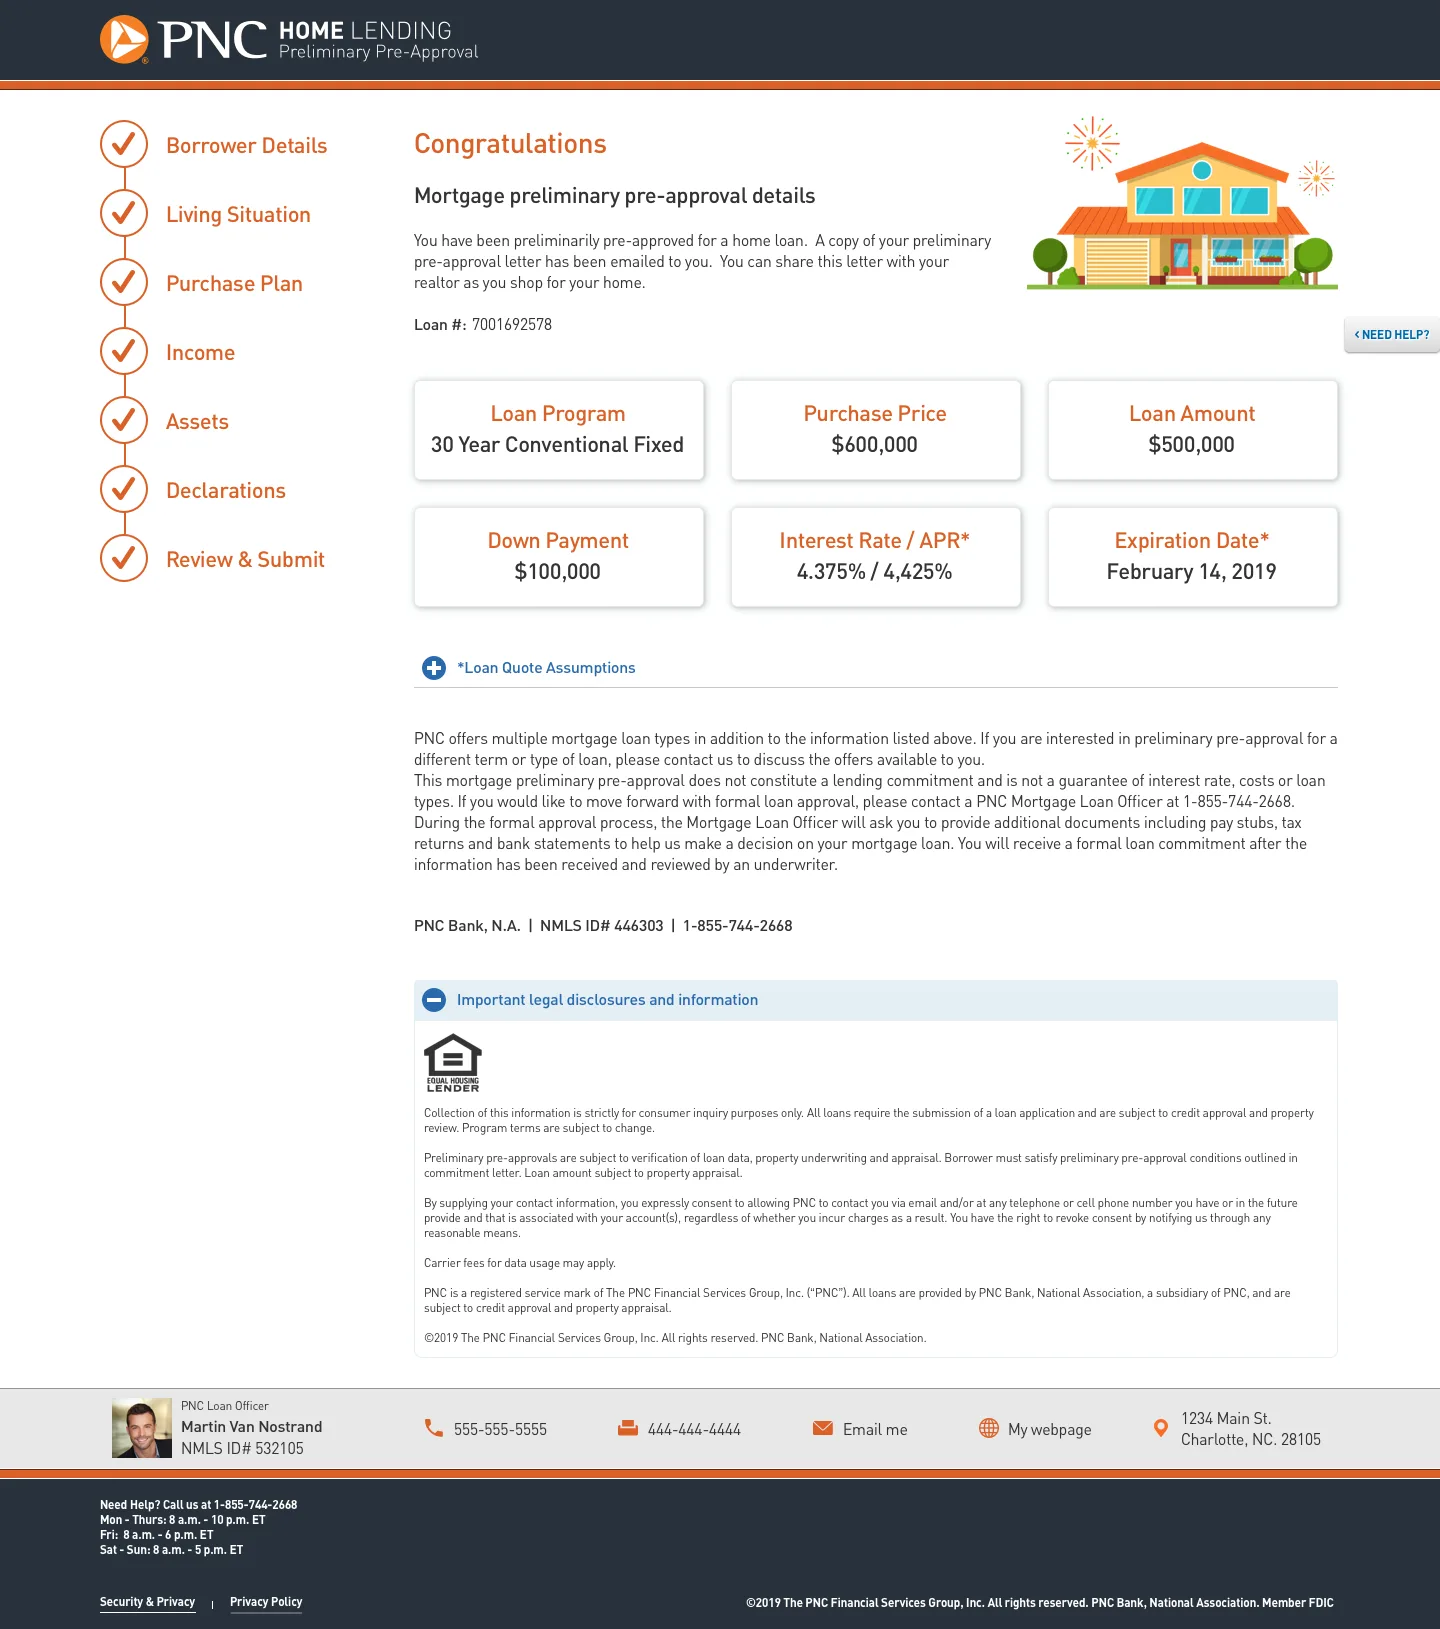
The result, the detail behind it, and the next step stay readable on both devices — and stay dependable for the loan officer reviewing the same record.
BOTH SIDES OF THE SAME RECORDWhere these numbers come from. Sprint count, testing cadence and production status are from the programme record. This work shipped in 2019 and PNC has iterated on it since, so the screens here are what I designed and what went live rather than what is on the site today.
This case has no adoption percentage attached to it, and I would rather say so than invent one. What it has instead is the strongest proof a design can have: it is public, it is still running, and you can go and use it yourself.
Federal requirements could not be negotiated away. The work was finding the freedom that existed inside them — a harder and far more common brief than a blank page.
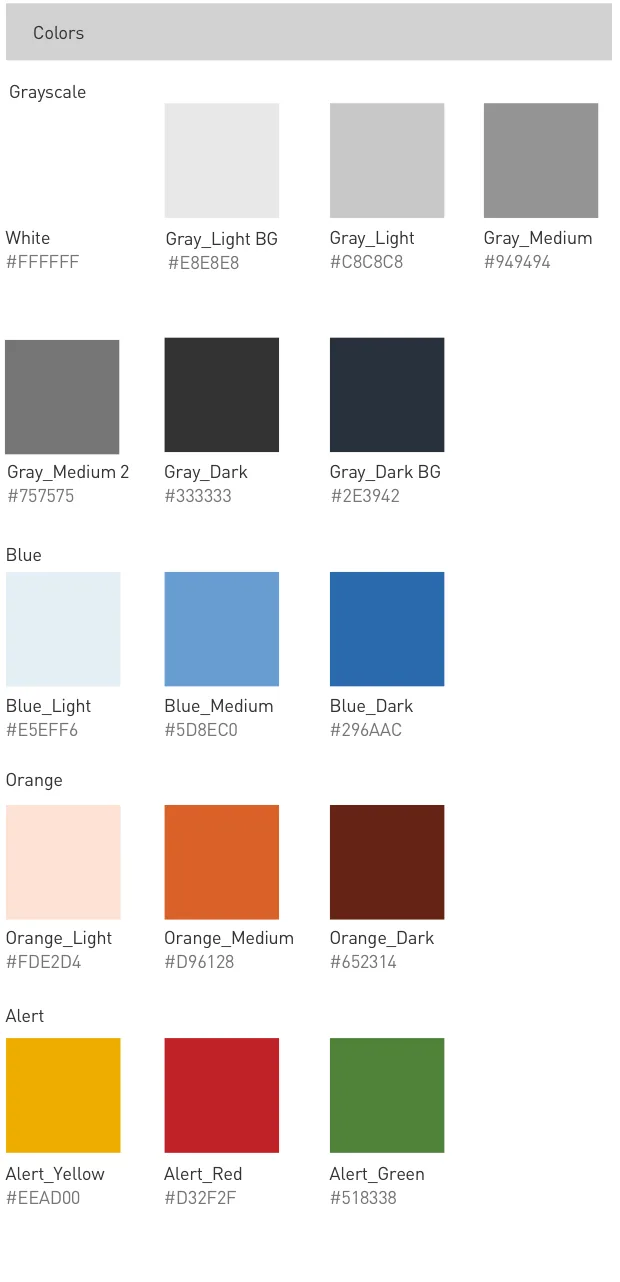
A kit of small reusable parts with shared spacing, type, error handling and states, so every lending product feels like one family without all becoming identical.
Legal and compliance joined the two-week working loop rather than reviewing at the end. That is how constraints became inputs instead of vetoes.
Real customers every six to eight weeks across 16+ two-week rounds, with each round’s findings folded into what the team tested next.
This shipped for one of the largest banks in the US and is still the live public experience. The least deniable evidence in this portfolio.
Want the reasoning, the research and the screens?
PNC's lending products, rebuilt: one shared system across laptop and phone, and an application that works out which questions are actually yours — so borrowing feels calm without a single legal requirement being dropped.
The old form put the bank's entire complexity in front of every applicant. People read a question that had nothing to do with them as evidence they had done something wrong.
I led the journey, the shared component system, the testing rhythm and the build detail — across UX, engineering, legal, compliance and marketing.
It is the public experience today: real mortgage applications, and the real bank-side approvals that follow them.
In the United States, a mortgage application is a federal form. So this was never a story about deleting questions.
What it must contain is fixed by law and by the organisations that buy mortgages from banks afterwards, like Fannie Mae. A bank cannot decide to ask less, and a designer certainly cannot.
One of the largest banks in the US, mid digital transformation: rebuilding the public application for every lending product, on laptop and on phone.
Not only the customer — also the loan officer who reviews and approves it. Vagueness on one side becomes a phone call on the other, so fixing one by burdening the other would not have counted.
Main home, second home or rental. It changes your rate and the rules.
A fixed block of yes/no questions everybody has to answer. Not removable.
Payslips, tax returns, employer confirmation. Genuinely mandatory.
Meaningless to a first-time buyer. The old form asked everybody.
Two vocabularies collide here: mortgage regulation and design process. Any term with a dotted underline will explain itself if you hover or tap it, and the glossary below holds all of them in one place.
The form works out which questions are yours, and shows you only those.
Taking out a mortgage was needlessly long and, worse, exhausting. Years of inherited practice had layered in intermediaries, back-and-forth and approvals. The old application asked every customer every question, whether it applied to them or not — and testing showed those irrelevant fields created real anxiety: “should I be filling this out?”
I led the strategy around one hard constraint: redesign the journey completely while satisfying every legal and compliance requirement. None of the information could disappear, so the product had to get clever about when, why and for whom each question appeared.
I led user interviews, observation in people’s own homes and offices, competitor analysis and journey mapping, then reconciled all of it with government, legal and compliance requirements. User types built from real PNC usage data, not from imagination, gave each kind of borrower a journey before a single screen was drawn.
Mapping the journey made the invisible dependencies visible: what customers actually knew at each point, what paperwork they had to hand, what the bank was obliged to check, and exactly where doubt crept in. That let the team separate the genuine legal requirements from habits inherited from the old system. The design opportunity lived entirely in that gap.
The interviews and journey work showed the same thing repeatedly: anxiety rose whenever customers could not tell why a question was being asked, or whether it was even meant for them. The fix was an experience that keeps explaining itself — through relevance, sequence, and behaving the same way on every device.
The application still captures everything the law requires. What changed is that the software decides when a field becomes relevant, so customers see their own path through it instead of the entire rulebook.
A long form became a sequence of small, understandable commitments. Sensible grouping, honest progress and a real review step replaced the feeling of facing an undifferentiated wall.
Laptop and phone share the same ordering, the same wording and the same behaviour. Moving to a smaller screen changes the layout, but what the customer already understood comes with them.
A mortgage application is really a branching conversation. Each answer removes the questions that were never yours, keeps every one the law requires, and carries your progress from laptop to phone.
Buying or remortgaging, what kind of property, who is applying — that establishes which branch you are on.
The fields that do not apply to you recede, and the next small decision becomes the only obvious thing to do.
A clear summary reflects the path the customer actually took, on either device.
More changed than the surface. The old experience exposed the structure of the bank: one dense page organised around everything the institution might ever need. The redesign exposes the structure of the customer’s task: a clear place to start, language people recognise, and a sequence that earns each next question.
Showing only what is relevant also made the review step worth having. By the time customers reach confirmation they are reading back the path they actually took, rather than checking another wall of fields line by line. The surface is calmer because the logic underneath is doing more work.
Paper sketches are cheap to test and cheap to throw away. Whatever survived became rough grey layouts, then finished screens built on a shared component kit of small reusable parts — so every lending product feels like part of one family while keeping its own character.
Each step up in finish answered a different question. Paper established whether the order made sense at all. Grey layouts tested what stood out and whether the wording landed, without anyone arguing about colour. The kit proved the winning patterns repeated across teams and screen sizes. Anything that looked finished came last, once the behaviour had earned it.
A good mortgage flow can still fail if its logic cannot be explained to legal, its parts cannot be reused by engineering, or its wording drifts between products. So the work extended past screen design into a way of making decisions together.
I used every two-week sprint to produce a prototype concrete enough for people to react to. Legal and compliance constraints arrived as design inputs rather than late approvals, and marketing, engineering and UX could all point at the same annotated behaviour instead of carrying three private interpretations into the build.
That discipline produced a shared component kit that worked at every screen size: common spacing, type, parts, error handling and states. Individual lending products kept their own needs, but customers stopped having to relearn the bank every time they moved between them.
I treated the phone as a journey in its own right, not a smaller copy of the laptop. The same parts and the same logic, rearranged around one clear action at a time, with your progress preserved when you switch device mid-application.
Shared parts, shared error checks and saved progress keep the two screen sizes inside one experience, rather than letting mobile drift into a separate product.
Income and application details arrive in a deliberate order on either screen.
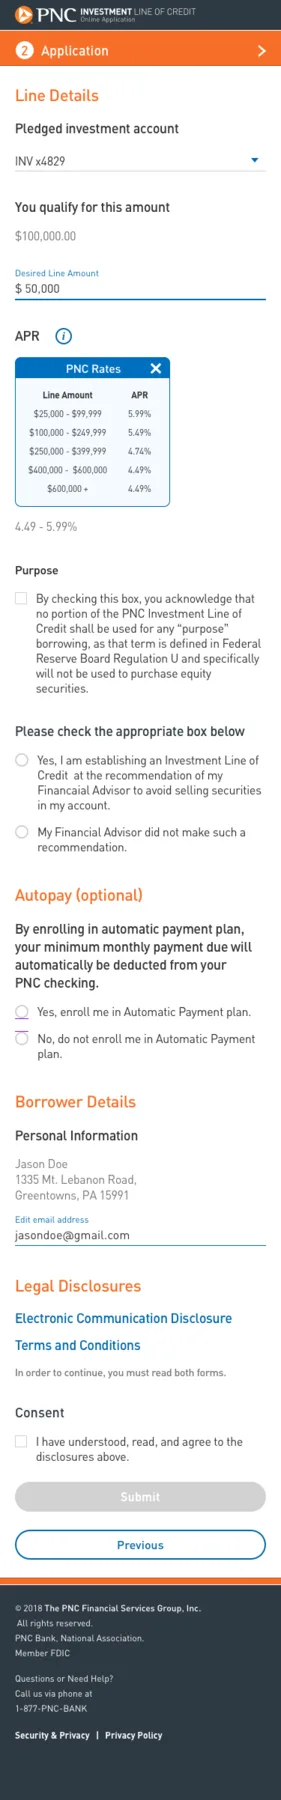
The same navigation and the same form rules keep the next decision recognisable at any screen size.
Review and processing states explain what has happened and what comes next.
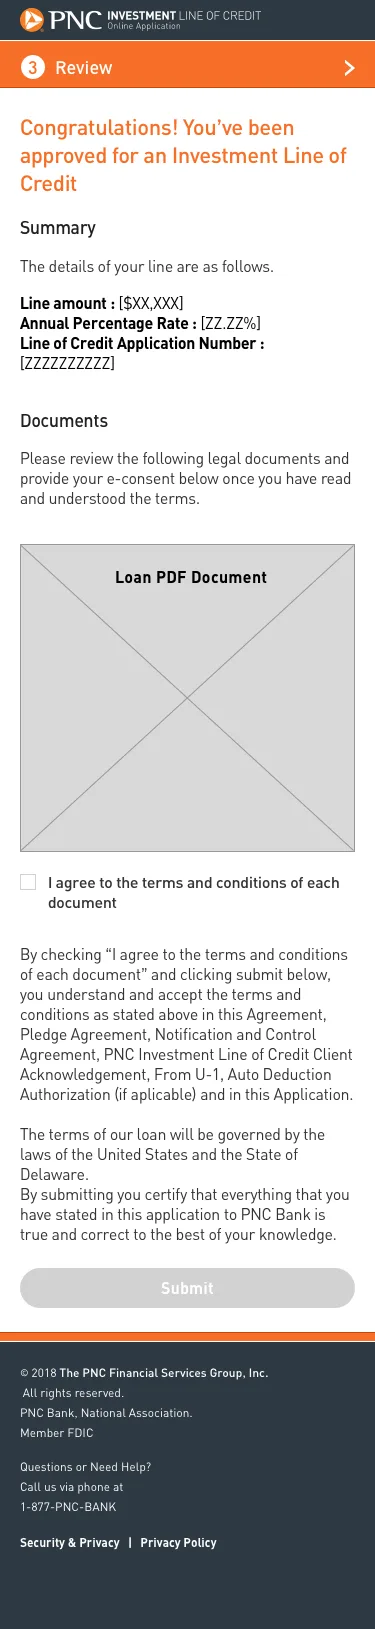
The final state keeps the result, details, and next action legible on both devices.
I ran testing every six to eight weeks — with real customers and with the people responsible for approving the journey — then fed what we learned into the next two weeks of work. The outcome: a mortgage application that knows when to ask, when to explain, and when to get out of the way.
Questions that did not apply to you simply never appeared. Customers stopped reading an irrelevant field as evidence that they had done something wrong.
Smaller groups of questions, a real review step and honest progress gave the application a human pace — without hiding the seriousness of the assessment behind it.
Shared parts and written-down rules for each screen size carried the same wording, the same checks and the same saved progress from laptop to phone — and from customer to loan officer.
Real customers use PNC Home Lending to start and advance mortgage applications, right through loan-officer review and approval. The public experience is still live today, carrying the same idea — ask only what is relevant, behave the same everywhere — into one of the most consequential decisions most people make.
There are shorter versions of this same project.
The moment a borrower sees what they have been approved for — the highest-stakes screen in the flow, annotated as it went to engineering. Click to zoom.
Click to zoom
Line heights, type sizes, padding, column gaps and every interaction state written onto the design. There was no shared component kit to appeal to, so the drawing had to carry the whole contract with engineering.
A borrower reads this screen in a state of anxiety. Anything that competes with the amount delays the only question they actually have.
Everything the law requires is present. It is sequenced so the mandatory language arrives after the answer rather than in front of it — the requirements stayed; the burden moved.
The same content on a phone reorders rather than shrinking. A borrower who started on a laptop and finished on a phone should recognise the screen, not relearn it.